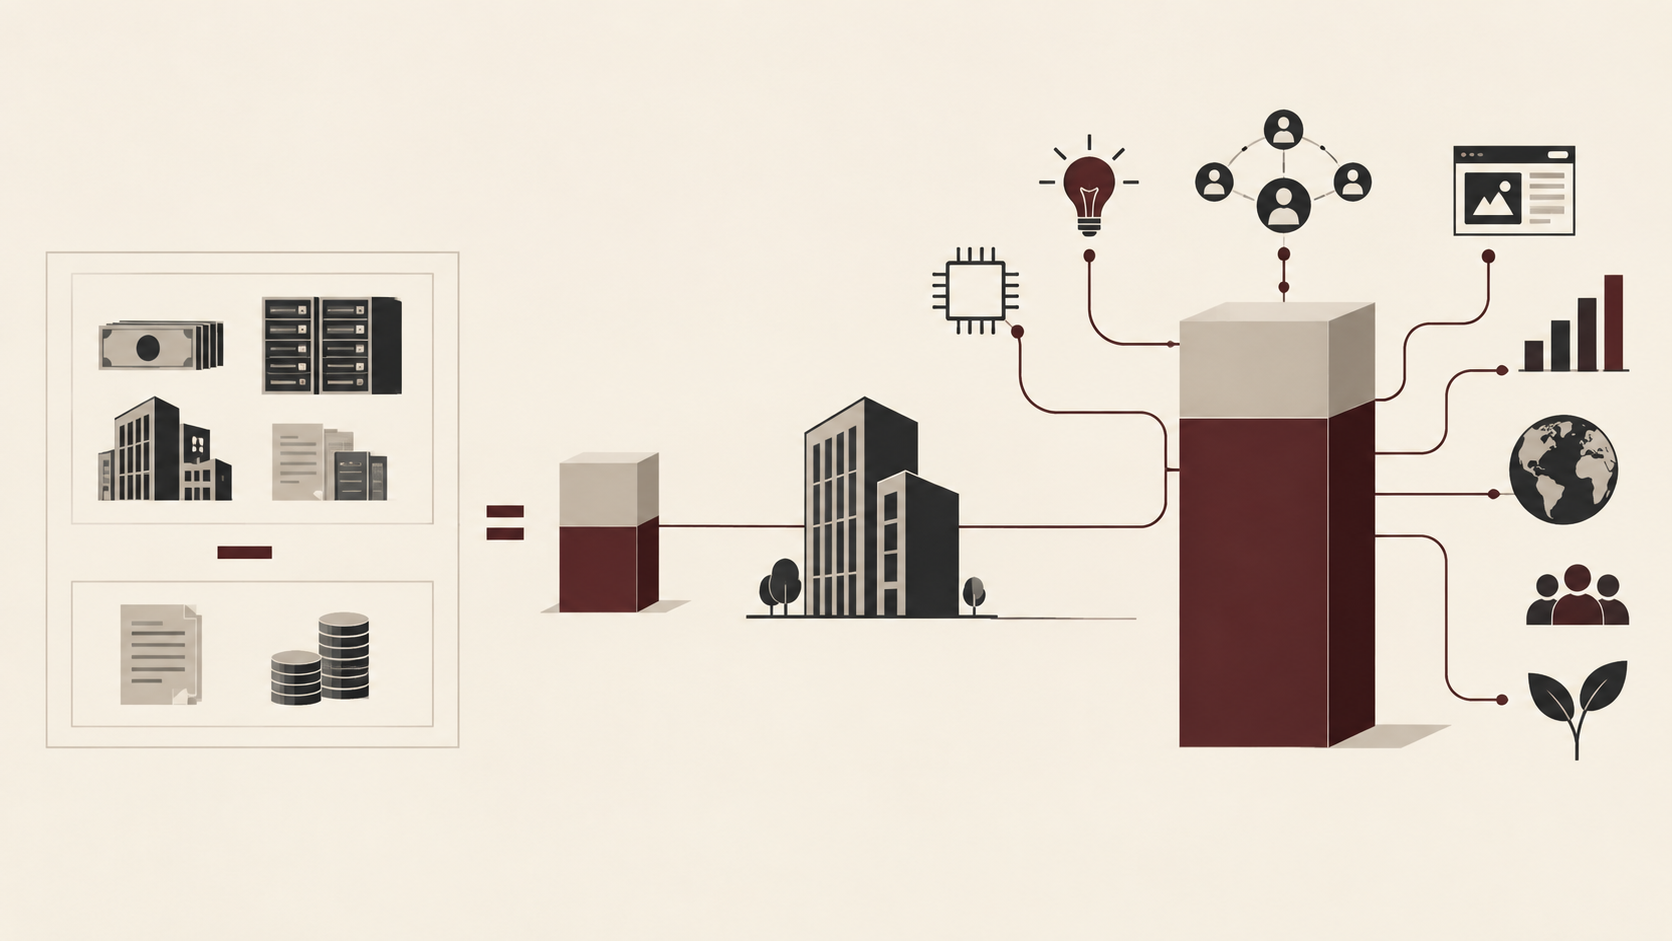
Meta reported $217.2 billion in stockholders’ equity at the end of 2025, while its market capitalization was roughly $1.66 trillion around the same date. Book value represents recognized assets minus liabilities under accounting rules; market value represents what investors are willing to pay for the company’s shares. Internally developed capabilities and investments such as R&D do not necessarily become separately recognized balance-sheet assets, even when investors expect them to create future economic value. A high market-to-book ratio reflects expectations about future profitability, growth, intangible capabilities and risk — not simply unrecorded assets.
- Meta reported $217.2 billion in stockholders’ equity at the end of 2025, while its market capitalization was roughly $1.66 trillion around the same date.
- Book value represents recognized assets minus liabilities under accounting rules; market value represents what investors are willing to pay for the company’s shares.
- Internally developed capabilities and investments such as R&D do not necessarily become separately recognized balance-sheet assets, even when investors expect them to create future economic value.
- A high market-to-book ratio reflects expectations about future profitability, growth, intangible capabilities and risk — not simply unrecorded assets.
At the end of 2025, Meta Platforms reported $217.2 billion in stockholders’ equity on its balance sheet. Around the same date, the company’s market capitalization was roughly $1.66 trillion.
That is a difference of more than seven times.
At first, the gap can seem strange. If the balance sheet says shareholders have $217 billion of equity in the company, how can investors collectively value those shares at well over $1 trillion?
The answer lies in what the two numbers are actually measuring.
What Does Book Value Measure?
Book value of equity comes from the balance sheet.
At its simplest:
Book Value of Equity = Assets − Liabilities
The Financial Accounting Standards Board defines equity as the residual interest in a company’s assets after its liabilities are deducted. In other words, it represents the accounting value attributable to shareholders under the rules used to prepare financial statements.
Meta illustrates the calculation clearly. As of Dec. 31, 2025, the company reported $366.0 billion in total assets and $148.8 billion in total liabilities. The difference was $217.2 billion in stockholders’ equity.
But that number should not be interpreted as an estimate of what the entire business could sell for.
A balance sheet is built according to accounting recognition and measurement rules. Some assets are recorded at historical cost less depreciation or amortization, some are measured using other accounting methods, and some economically valuable resources may not appear as separate assets at all.
Book value is therefore an accounting measure of net assets, not a stock-market valuation of the business.
The Market Is Asking a Different Question
Market value — or market capitalization for a publicly traded company — is calculated differently:
Market Capitalization = Share Price × Shares Outstanding
Rather than starting with the accounting values assigned to assets and liabilities, the market price reflects what investors are willing to pay for ownership in the company.
That means investors are considering what the business may be capable of producing in the future.
Expected earnings and cash flows matter. So do growth opportunities, competitive position, technology, customer relationships, risk, and the return investors require for putting capital into the company.
If investors believe a company can use its existing resources to generate substantial future profits, its market value can be far higher than the equity recorded on its balance sheet.
Meta provides a useful example.
The company generated $201.0 billion in revenue and $83.3 billion in operating income in 2025. Its Family of Apps — including Facebook, Instagram, Messenger and WhatsApp — averaged 3.58 billion daily active people in December 2025.
Those operating capabilities are central to the business investors are valuing. But they cannot simply be translated into a line on the balance sheet saying that Meta’s global user network, advertising system or ability to develop future products is worth a specific amount.
Not Everything Valuable Becomes a Balance-Sheet Asset
This distinction becomes particularly important for businesses built around intangible resources.
A factory, server or building can generally appear as an asset on a balance sheet when accounting requirements are met. Internally developed knowledge, organizational capabilities and other intangible investments can receive very different accounting treatment.
Research and development is a useful example.
Meta reported $57.4 billion in R&D expense in 2025, up 31% from the previous year. The spending included employee compensation, infrastructure and technology development, including work related to the company’s AI initiatives.
From a business perspective, some of that spending may help create products, technologies and capabilities that produce benefits for years.
From an accounting perspective, however, R&D costs are generally recognized as expenses rather than accumulated into a large internally generated R&D asset on the balance sheet.
That distinction has long attracted attention from researchers studying the gap between book and market values. Research published through the National Bureau of Economic Research has examined how intangible capital omitted from conventional balance sheets can help explain why market values differ substantially from reported book values, particularly among R&D-intensive businesses.
This does not mean that the difference between market value and book value is simply the “value of intangible assets.” The market premium can reflect many things, including expected future profitability, growth opportunities and investor assessments of risk.
But it helps explain why the balance sheet alone cannot tell investors what a company is worth in the stock market.
Same Company, Two Different Measurements
The distinction can be reduced to two different questions.
Book value asks: What is the accounting value of the company’s recognized assets after its liabilities?
Market value asks: What are investors willing to pay today for ownership of the company and the future economic benefits they expect that ownership to produce?
That is why the two figures do not need to match.
A company can have relatively modest book equity while operating a business that investors expect to generate large amounts of future cash flow. Conversely, a company’s market value can move quickly even when its reported book value changes very little, because share prices respond continuously to new expectations.
The difference also helps explain why comparing companies only by the size of their balance sheets can be misleading. Two businesses with similar book equity can receive very different market valuations if investors expect their future profitability, growth or risks to differ.
The Gap Is Information, Not an Accounting Error
A large market-to-book gap does not automatically mean that a balance sheet is missing something it should have recorded. Nor does it automatically mean that investors have correctly valued every future opportunity.
The two measures serve different purposes.
Financial statements organize the assets, liabilities, equity, revenues, expenses and cash flows of a business under established accounting rules. Markets then use that information — alongside expectations about the future — to determine what investors are willing to pay for the company’s shares.
For a business like Meta, the $217 billion book value and roughly $1.66 trillion market value therefore tell two different stories about the same company.
One describes the company through accounting.
The other reflects the market’s expectations about what the business can produce from here.
The important lesson is not that the stock market knows a company’s “real” value while accounting does not. The two systems answer different questions. Financial statements describe the business using standardized accounting rules; markets use that information to form expectations about the future. The distance between those numbers can therefore reveal something important about where investors believe a company’s economic value comes from.
- SEC filing Meta Platforms, Inc. — 2025 Form 10-K, filed Jan. 29, 2026
- Company IR Meta Platforms — Meta Reports Fourth Quarter and Full Year 2025 Results, Jan. 28, 2026
- Accounting standards Financial Accounting Standards Board — The Framework of Financial Accounting Concepts and Standards
- Academic research NBER — Hulten and Hao, “What is a Company Really Worth? Intangible Capital and the ‘Market to Book Value’ Puzzle,” Dec. 2008
- Market data Stock Analysis — Meta Platforms Market Cap History, Dec. 31, 2025 observation